Hello and welcome to Alts Cafe.
A curated pour of the week’s most important alt investing stories, customized and brewed to your liking.
Table of Contents
Highlights
- International Investing: The global bond selloff drives long-term borrowing costs to decade highs worldwide
- Startups & VC: X Money pays 6% on deposits without a banking charter
- Sports: A new Surfing Super League will franchise Australia’s $2.7 billion surf economy into eight teams for a 2028 debut
- Prediction Markets: The CFTC seats Kalshi and Polymarket on its new advisory panel
- Music & Film: California caps film tax credits at $5 million per company
- Crypto: The SEC proposes Regulation Crypto Assets with two registration exemptions
- Collectibles, Culture and Luxury: Jordan’s Last Dance jersey carries a $15 million estimate
- Private Equity & Private Credit: Blackstone’s BCRED books $1.85 billion of unrealized losses
- Real Estate: Data centers push Northern Virginia to the top of CRE
- Precious Metals and Gems: Central banks buy a record 289 tonnes of gold into a falling price
- Artwork: Collectors sue a London gallery over a cancelled first purchase
- Farmland: Lake Mead and Lake Powell hit record lows at the same time
- Wine, Whiskey & Spirits: Burgundy brings in its earliest harvest in nearly 500 years
- Other: Jane Street loses $15 billion in a month
International Investing

Around the world…
- 🇺🇸 The global bond selloff pushes US 30-year Treasury yields to their highest since 2007, with French borrowing costs at 2008 levels, German 30-year paper back at 2011 levels and Japanese long bonds near an all-time high
- 🇨🇳 Humanoid robot maker Unitree surges 460% on debut after a $904 million IPO in Shanghai, pricing the first listed humanoid maker in mainland China at 36 times sales
- 🇰🇷 Korea‘s revised Commercial Act takes effect on September 10, capping controlling families at 3% of voting power when minority shareholders elect audit committee members, while the Kospi fell almost 6% in a single session
- 🇦🇺 Australian VCs Blackbird and Airtree mark Canva down 17% to $34.9 billion, while offshore venture investors argue publicly that it could be worth $12 billion or less
Why it matters: The long end stops behaving
For most of four decades the question “why are long rates here” had an inflation answer. This week it stopped working.
Thirty-year Treasury yields hit their highest since 2007, French borrowing costs reached 2008 levels, German thirty-years traded back at 2011 and UK equivalents approached 6%, all while headline US inflation was cooling to 3.4%.
Prices falling and long yields rising at the same time is the tell that something other than the central bank is setting the price. That something is competition for savings.
Governments are running large deficits into an aging demographic, and the AI buildout has become one of the biggest private investment programs in modern history. Alphabet paying a record near-7% for its first Australian bonds is what that looks like when the domestic bid runs thin.
The 1990s tech boom is the wrong comparison, because Washington was cutting debt then and is adding it now.
For allocators the practical consequence is that the discount rate on every long-duration asset just moved.
Music & Film
- California’s June budget bill caps the film tax credits any single company can claim at $5 million a year through 2029, retroactively gutting a program the state had just doubled to $750 million
- Suno signs a global licensing deal with BMG and caps Pro subscribers at 20 downloads a month, settling prior use of BMG recordings in the process
- A deal taking shape would fully exempt indie productions while leaving studios capped with faster refunds instead, with the legislative session closing on August 31
- Spider-Man: Brand New Day passes $2 billion worldwide in three weeks, the second-fastest ever, lifting the domestic year to $6.86 billion and 19% ahead of last year
- Cinema United reverses course and urges Paramount Skydance and California’s attorney general to settle the Warner suit, fearing a trial in March 2027 freezes the release calendar
- Peacock raises prices across every plan, its fourth increase in four years and the first since the service turned a profit
- James Franco becomes the first Oscar nominee to headline a vertical microdrama, under SAG-AFTRA’s new Verticals Agreement covering mobile shoots budgeted under $300,000
- YouTube changes how it counts views to match TikTok and Instagram, inflating the headline number while keeping the old measure as engaged views
- Warner Music’s Robert Kyncl argues Netflix should license music, noting music videos account for 33% of YouTube watch time against 6% for video podcasts
Why it matters: California taxed away its own incentive
Last year Hollywood won a fight it had been losing for a decade, more than doubling California’s film incentive to $750 million a year.
Then a June budget bill capped the credits any single company can claim at $5 million annually, and did it retroactively. ]Paramount earned $37.7 million in credits and can now collect $5 million a year. Disney earned $45 million and is in the same position.
Productions already wrapped and paid for are holding paper worth a fraction of what was promised, collectible over nearly a decade.
Lawmakers say they never meant to include film, which is probably true and completely beside the point. The financing consequence is the one that matters, because a tax credit is not a rebate, it is collateral.
Independents sell theirs to raise production money, which is why the emerging fix exempts indies entirely while leaving studios capped with faster payment. A credit that pays out over ten years at $5 million a year is worth far less to a lender than one that pays next year, and that discount flows straight into what a film can be made for.
Sacramento’s real problem is that it cannot exempt Hollywood without inviting every technology lobbyist in the state to ask for identical treatment.
The session ends August 31. Location scouts in Atlanta and London are already refreshing their inboxes.
Did you know we finance Hollywood films?
Well, we do! And on Tuesday, September 15, we’re screening one of them.
We’re taking over Nitehawk Cinema in Brooklyn for a private showing of The Dutchman, featuring Kate Mara and Andre Holland.

Film bridge lending is one of the most compelling and least understood corners of alternative investing.
Before the lights go down, we’re renting out Nitehawk’s Lo-Res bar to explain how our film lending joint venture, Launch Film Finance, originates film bridge loans.

If you’re in NYC, don’t miss this.
- Sep 15, 5-9pm.
- $99. Drinks and dinner come to your seat,
- 32 ppl capacity
Startups & VC
- X Money goes live nationwide with 6% on deposits, a Visa card paying 3% cashback and up to $10 million of swept FDIC coverage, all without X holding a banking charter of its own
- Anthropic tells investors its annualized revenue run rate hit $65 billion at the end of July, a sevenfold rise in a year, with second-quarter revenue of $11.5 billion and reports of an IPO that could reach $2 trillion
- SpaceX completes its $60 billion acquisition of Cursor, the largest venture-backed exit on record, pairing the fastest company ever to $100 million of revenue with xAI’s compute
- Databricks raises $5 billion at a $190 billion valuation led by Coatue, on a $7 billion revenue run rate growing 80%, after asking for $1 billion and being offered $15 billion
- AI coding startup Cognition opens talks to raise at a $40 billion valuation, up from $26 billion three months ago and twenty times its mark two years back
- Forty companies joined the unicorn board in July, the highest count in years, extending a first half that already produced more billion-dollar startups than all of 2025
- Surveillance drone maker Tekever opens talks at a €5.5 billion valuation, roughly five times its Series B mark from May 2025, as European defense drone rounds reprice across the board
- Palmer Luckey’s banking startup Erebor nears a $1.5 billion raise at an $8 billion valuation, nearly double its earlier mark, having crossed $100 million of annual recurring revenue
- Roughly 40% of US private-equity-backed companies have been held longer than seven years, representing $860 billion of net asset value, with 2021 vintage funds returning just 0.14x
- Twenty-five executives have left OpenAI since January 2024, a run that analysts now call a red flag before the IPO
- Notion reaches an estimated $865 million of revenue growing 82%, while quietly retreating from its attempt to rebuild the productivity suite
Why it matters: A 6% deposit rate nobody can earn
Federal funds sit around 3.5%, so paying 6% on demand deposits puts X roughly 225 basis points above the risk-free rate, on money customers can withdraw tomorrow.
No net interest margin produces that. Which means the 6% is not really a yield, it is a customer acquisition cost, funded out of subscription revenue, interchange and a parent company willing to buy distribution.
The structure underneath makes the same point. X does not have a banking charter. X Payments holds money transmitter licenses in 41 states, the deposits sit at Cross River Bank, and the $10 million of coverage comes from a sweep program spreading balances across partner banks rather than from any balance sheet X controls.

X has also published no Truth in Savings disclosure, so the rate is variable, changeable at will and closer to an advertisement than a term.
None of this threatens anybody’s deposit base yet, with 4.4 million Premium subscribers against a claimed 600 million monthly users.
What is being assembled is optionality: a licensed money transmission stack, a bank partner, a card program and enormous distribution, built in the one jurisdiction where the consumer regulator that would normally supervise all of it was dismantled last year.
The thing to watch is the GENIUS Act carveout letting private companies issue payment stablecoins without the approvals public companies need. X has the distribution and it has the statutory path. If those balances ever migrate from Cross River into an X-issued token, the deposit insurance does not travel with them.
Sports
- A new Surfing Super League will franchise Australia’s $2.7 billion surf economy into eight teams for a 2028 debut, paying surfers a fixed $11,000 a week on a LIV Golf template
- Mark Walter sold the Lakers at a 20% gain in under two years while under federal investigation for allegedly lending roughly $20 billion of insurance customer money to companies he controls, against $1.4 billion originally disclosed
- Walter and Todd Boehly open talks to sell their Chelsea stakes to Clearlake Capital, days after the Lakers deal and amid reports he needs roughly $5 billion more before year-end
- Jeanie Buss contests her siblings’ vote to sell the family’s remaining 17.8% stake, arguing the family trust obliges them to keep her as controlling owner
- Madison Square Garden Sports posts record results on the Knicks title run, including $182 million of playoff revenue, or more than $20 million per home game, with the stock up 100% in a year
- 777 Partners files for Chapter 11 with more than $2 billion of debt, two years after its failed takeover attempt for Everton and an FBI indictment of its cofounder
- Mat Ishbia’s UWM books a $603 million loss on interest rate bets and takes a $2.05 billion Oaktree rescue at 10%, reviving questions about whether a margin call forces a sale of the Phoenix Suns
- Fenway Sports Group adds a women’s TGL franchise alongside Boston Common Golf, joining owners including Steve Cohen and Alexis Ohanian
Why it matters: The sport that could never be scheduled
Surfing has never worked as a broadcast product for a reason that has nothing to do with popularity: you cannot schedule the ocean.
Contests run on waiting periods, windows open at dawn on a few hours’ notice, and a network buying the rights has no idea which weekend it is actually buying.
The Surfing Super League’s answer is to stop pretending the swell matters. Eight regional franchises, eight consecutive weekends on Australia’s East Coast, relay heats with four surfers a side, and fifteen fixed 90-minute matches in a Saturday and Sunday afternoon slot, adding up to 30 hours of guaranteed programming whatever the conditions. The surfing is the content; the schedule is the asset.
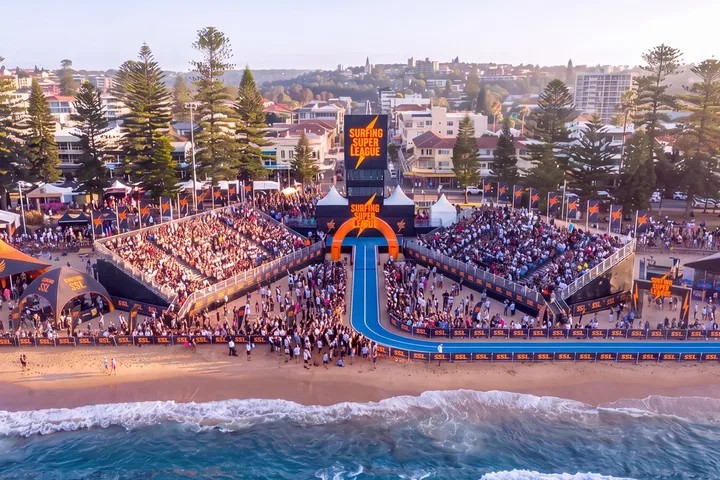
Everything else follows from that. Athletes go onto fixed contracts instead of prize money, $89,000 for the season and equal across men and women, which is the LIV Golf move of guaranteeing the talent, buying certainty and accepting that the purists will hate it.
The league will own all eight teams at first and sell them progressively across four seasons, forecasting values above $8 million after year one and $30 to $40 million by season three, with capital able to enter at either the league or the franchise level.
Australia has 6.3 million surfers and recreational surfing contributes $2.71 billion a year, yet the sport captures a fraction of the sponsorship and broadcast money that reaches the NRL or the Big Bash. The incumbent is not defending that gap. The World Surf League is exploring a sale through the Raine Group after failing to close Netflix in 2021, with top prize money down from $100,000 in 2019 to $80,000 this year.
Dirk Ziff has funded professional surfing for thirteen years and is now looking for the exit. Somebody is about to find out whether the problem was the sport or the format.
Prediction Markets
- The CFTC seats Kalshi, Polymarket and DraftKings on its new innovation panel, whose first meeting on August 20 puts prediction markets on the agenda alongside crypto and AI agents
- Kalshi and Polymarket now carry private valuations of $22 billion and $15 billion, against $2 billion and $1 billion a year ago
- Kalshi is separately reported to be seeking capital at a $40 billion valuation, which would widen its lead over its rival to nearly three times
- Midterm contracts on both venues currently favour a Democratic sweep, on $12.5 million of combined volume across House and Senate markets
- Michael Mauboussin publishes a 58-page study arguing crowds in prediction and betting markets are genuinely hard to beat because they aggregate known information with unusual efficiency
- Trump Media formally scraps its Truth Social prediction market, agreeing instead to market Crypto.com’s platform to its own users
Why it matters: The regulator invites the industry inside
Two years ago prediction markets were fighting the CFTC in court. This week the agency seated Kalshi, Polymarket and DraftKings on its Innovation Advisory Committee and put event contracts on the agenda of its first meeting.
That is a different relationship entirely. What it settles is federal legitimacy. A venue with a seat at the rulemaking table is not a venue anyone expects to be shut down, and removing that tail risk is the single cleanest explanation for why Kalshi and Polymarket went from $2 billion and $1 billion a year ago to $22 billion and $15 billion today.
What it does not settle is everything happening one level down. New York’s City Council is investigating how these platforms advertise, state gaming regulators have their own view, tribal operators are litigating, and the integrity problem of traders who knew outcomes in advance has not gone away.
Federal blessing plus local hostility is precisely the position sports betting occupied in 2019, and the lesson from that cycle is that the legal fight is never the expensive one. The marketing fight is.
Watch whether the contracts these venues choose to list get more conservative now that the people writing the rules are in the room.
Crypto
- The SEC proposes Regulation Crypto Assets, its first offering framework for tokens, with two registration exemptions including one covering raises up to $75 million
- Trump’s World Liberty Financial wins preliminary approval for a national trust bank charter, letting it issue the USD1 stablecoin nationwide without financial intermediaries
- The Bank of Russia moves to let retail investors trade bitcoin, ether and tether, capped at about $3,600 a year and conditional on passing a test
- Strategy sells another $108.6 million of bitcoin, its fourth sale this year, having realized more than $102 million of losses and bought nothing since June
- The SEC charges crowdfunding platform Netcapital with fraud for allegedly inflating revenue by 345%
- Sub-Saharan Africa took in $205 billion of on-chain value over a year, with stablecoins now roughly 43% of regional transaction volume
- Uniswap falls 14% in a week even as on-chain activity holds up, because the protocol retains far less in fees than competitors such as Hyperliquid
Why it matters: The SEC finally writes the rulebook
For a decade the American crypto industry has argued that it could not comply with rules that did not exist. Regulation Crypto Assets removes that argument.
The proposal creates a purpose-built offering framework with two exemptions, including one for raises up to $75 million, which is the first time the agency has described how a token can lawfully be sold in the United States rather than only when selling one is illegal.
Commissioner Peirce framed it as filling the regulatory tank; the practical read is that enforcement-first policy has been formally retired.
Three consequences follow.
- First, compliance costs land on issuers rather than lawyers, and any project operating offshore for jurisdictional reasons now has to decide whether it wants a US investor base badly enough to register.
- Second, it takes pressure off the CLARITY Act, since much of what market structure legislation was meant to fix can now be done by rule, which is faster and also far easier to reverse.
- Third, it arrives in the same fortnight the OCC handed a president-linked firm a national trust bank charter for its own stablecoin, which is the sort of coincidence that makes a rulebook harder to defend as neutral.
Clear rules are worth more to this industry than favourable ones. Whether these survive the next administration is the only question that really counts.
Collectibles, Culture and Luxury
- Jordan’s Game 3 jersey from the 1998 Finals heads to Joopiter carrying a $10 to $15 million estimate, against the $10.1 million record his Game 1 jersey set
- Amazon is buying rare books, cutting off their spines and scanning them, because pre-AI text is guaranteed not to be synthetic
- The Shelby becomes the most expensive American car ever sold at auction, while the Hagerty Supercar Index rose 30% over the past year on millennial and Gen Z bidding
- A 1997 Metal Universe Precious Metal Gems Michael Jordan sells for $1,473,989 on Alt, a record for any PMG, after the seller turned down a $900,000 private offer
- A one-of-one Macklin Celebrini Young Guns rookie sells for $1.28 million, the highest price ever paid for a modern hockey card
- A Wisconsin game shop turns out to have been sitting on 97 undocumented Mario cartridges, five of which graded a perfect PSA 10, after nearly selling them at $15 each
- Cooper Flagg’s one-of-one rookie debut patch autograph surfaces in Rhode Island after the Mavericks offered 32 years of season tickets for it
- Maradona’s Hand of God ball carries a $10 million estimate at Heritage this weekend, alongside a T206 Honus Wagner valued near $4 million
- Thieves have now taken 210 of the 320 gold Mozart statuettes placed around Salzburg for the composer’s 270th birthday
Why it matters: The artifact pulls away from the card
Two Michael Jordan records landed in the same week and they are not from the same market.
- A 1997 Precious Metal Gems card sold for $1,473,989, the most ever paid for a PMG of any year or player.
- Then his Game 3 jersey from the 1998 Finals was announced for auction at Joopiter with an estimate up to $15 million.
One is a seven-figure market. The other is an eight-figure one, and the gap has been widening for four years.

The reason is provenance rather than nostalgia. Cards are graded and effectively fungible inside a grade, which is what makes indices, fractional platforms and orderly price discovery possible, and it is also what caps them, because a PSA 10 is worth roughly what the last PSA 10 fetched.
A photo-matched game-worn jersey is a one-of-one attached to a specific night, and once the authentication chain became credible the ceiling came off. That credibility is recent and institutional.
Sotheby’s became the NBA’s game-worn partner in 2023, Christie’s opened a sneaker department in 2022, and Jordan’s Dynasty Collection sneakers cleared $8.03 million in 2024. This weekend supplies corroboration from another sport entirely, with Heritage offering Maradona’s Hand of God ball at a $10 million estimate in the same sale as a T206 Honus Wagner valued near $4 million.
The most famous card in the world is now expected to fetch less than half of a football.
Two cautions for anyone tempted.
- One-of-ones have no comps, so a mark is only ever as good as the last auction, and the buyer pool at $15 million is a few dozen people worldwide.
- And the seller here is a fashion-adjacent house rather than a sports specialist, which tells you the category is being sold as luxury rather than as sport.
Watch whether Joopiter clears $10.1 million on September 29. If it does, every photo-matched item sitting in a vault gets revalued.
Private Equity & Private Credit
- Blackstone’s BCRED books $1.85 billion of unrealized losses in the first half, more than triple its total for all of 2025, alongside rising redemption requests and a falling net asset value
- Silver Lake opens talks to take Workday private at a $43 billion valuation, which would rank among the largest software buyouts ever completed
- Evercore expects the private capital secondary market to reach $250 billion this year after a record $121 billion first half, with GP-led volume outpacing LP-led for the first time since 2022
- The University of California sells $1 billion of private equity stakes to HarbourVest at a discount above 10%
- Blackstone and La Caisse lead a C$2.5 billion investment for 25% of Aeroplan, Air Canada’s loyalty program, in the latest carve-out of a contractual cash flow stream
- Nelson Peltz’s Trian prepares a take-private bid for Wendy’s, sending the stock sharply higher, while KKR bids roughly $9 billion for Pennsylvania utility UGI
- Blue Owl’s GP stakes arm takes roughly 25% of tail-end secondaries specialist Hollyport, which manages more than $11 billion
- Banks are competing for underwriting roles on Anthropic’s growing pre-IPO credit line, the clearest sign yet that private credit now funds the listing pipeline itself
- Bloomberg counts thousands of buyout firms that have been comatose since 2021, operational and solvent but with no realistic path to an exit
Why it matters: The biggest nontraded credit fund marks down
BCRED is the flagship. It is the fund that proved retail investors would buy private credit at scale, and its marks are the ones every competing product gets measured against.
So $1.85 billion of unrealized losses in six months, more than triple the whole of last year, is not a fund-level event.
The important detail is that these are marks rather than defaults, which cuts both ways.
- Optimistically, unrealized losses reverse when spreads tighten.
- Pessimistically, marks moving this fast in a book that is supposed to be mostly senior secured first-lien paper suggests the underlying credits deteriorated faster than a quarterly valuation cycle can show, and that is the criticism private credit has never satisfactorily answered.
The redemption data is the tell to watch. Blackstone already capped withdrawals at BCRED in June, and requests are still rising. A semi-liquid vehicle experiencing simultaneous NAV declines and redemption pressure has exactly one lever, which is selling its most liquid assets and leaving remaining holders with the illiquid remainder.
Set that against the same asset class extending itself further up the risk curve, with banks now queuing to underwrite Anthropic’s pre-IPO credit line.
None of this is a crisis. It is the first honest test of whether a product built for permanent capital behaves when the capital decides it is not permanent.

Creators are building real businesses, and a whole new private financing layer is emerging to fund them: advances, revenue-share deals, credit lines, and catalog loans.
On October 6 we’re bringing the people writing those checks (and the people taking them) together in Los Angeles for an intimate evening of straight talk on how creator lending actually works.
Real Estate
- Northern Virginia becomes the top US commercial market on a 259% jump in sales driven by data centers, ending Dallas’s six-year run at number one
- Local data center bans have now passed 500 nationwide with bipartisan support, one of the few things Republicans and Democrats currently agree on
- Vantage Data Centers explores an IPO at a $100 billion valuation or an outright sale, in what would be the largest listing in data center history
- US housing starts fall 12.4% in July and 13.5% year-over-year, while building permits rose 5% to their fastest pace since February
- Redfin’s index shows home prices up 3.4% year-over-year, the fastest annual gain in a year, with San Francisco leading and every one of the biggest declines in Texas
- Builder confidence edges up to 35 on the NAHB index, a sixteenth month below 50 as high mortgage rates keep demand subdued
- Home Depot beats on revenue of $47.9 billion and its best comparable sales since 2022, with management describing the housing market as simply frozen
- Commercial and multifamily borrowing rose 16% year-over-year in the second quarter, with office and industrial lending leading the rebound
- Net-lease investment volume grew 13% year-over-year, with industrial up 28% while office volume fell 21%
- Four private islands totalling 520 acres in Michigan’s Lake Huron waters list for $2.3 million together, truck, tractor and two boats included
Why it matters: A CRE market where the tenant list fits on a card
Dallas held the top spot in American commercial real estate for six straight years. This week Northern Virginia took it on a 259% increase in sales, and essentially all of that came from data centers.
A traditional CRE market is diversified almost by definition: thousands of tenants across offices, retail, industrial and apartments, each responding to different local demand.

A data center market is the opposite. The buildings are enormous, the leases are long, and the credit behind them belongs to perhaps six companies on earth.
That is why the money is flowing, since hyperscaler credit is better than almost any office tenant, and it is also the entire risk. The scale being underwritten is now visible in the exit market, with Vantage exploring an IPO near $100 billion, which would be the biggest data center listing ever attempted. Texas alone has roughly 100 gigawatts of planned capacity, more than Virginia and Utah combined, and more than 500 local construction bans have now passed nationwide.
Set that against the residential market in the same week, where starts fell 12.4%, builder confidence spent a sixteenth month below 50 and Home Depot’s management called the market frozen.
Capital is voting decisively for compute over housing. It tends to do that right before somebody points out that housing shortages do not resolve themselves.
Artwork
- Two first-time collectors are suing London’s Alison Jacques gallery after their purchase of Monica Sjöö paintings collapsed when the artist’s estate allegedly questioned their seriousness as buyers
- Frieze moves its Seoul edition to a Zaha Hadid-designed convention centre from 2027, doubling down on Korea as the region’s fair capital
- Pavilion launches a Seoul edition promising to put art before commerce, the latest alternative fair pitched against fair fatigue
- A major Hiroshige woodblock collection heads to Christie’s, the largest to reach auction in years
- The Art Newspaper publishes a guide to artist agents and consultancies, mapping the services replacing galleries for artists who no longer want traditional representation
- An 18-year-old flipping abandoned storage units now clears $135,000 a year, after one $450 unit turned out to contain a Man Ray
Why it matters: When the estate gets to pick the buyer
Two collectors making their first serious art purchase agreed terms on works by Monica Sjöö, and then the sale collapsed because the estate questioned their seriousness. They are now suing.

Whatever the merits, the case exposes something the primary art market prefers not to discuss in public, which is that a gallery sale is not really a sale in the way any other market would recognise one.
Price is agreed, and then allocation happens, and allocation runs on a private assessment of whether the buyer will hold the work, lend it to institutions and generally improve the artist’s standing rather than flipping it into an auction two years later.
For a rediscovered artist with controlled supply, that vetting is the mechanism that creates the price in the first place. The tension is that it is entirely opaque and legally ambiguous, and it collides badly with a generation of buyers arriving from markets where money simply clears.
This is why the guide to artist agents and consultancies published the same week is more interesting than it sounds: an entire service layer is forming around artists who want to sell without accepting gallery gatekeeping, at exactly the moment gatekeeping is being litigated.
Art is the last major asset class where the seller chooses the buyer. Watch whether a court decides that is a preference or a contract.
Precious Metals and Gems
- Central banks bought a record 289 tonnes of gold in the second quarter, a fivefold jump from the first, during the steepest quarterly price decline in a decade
- Gold has since recovered to roughly $4,300 an ounce, up about 28% on the year, with central banks on pace for 850 tonnes across 2026
- Copper futures are up 44% over twelve months on AI infrastructure demand, with LME stocks falling for a 42nd straight session and BHP reporting a 30% rise in underlying profit
- The LME introduced emergency measures on August 14 to contain the squeeze, and by the following week the spread had widened further to about $543 a tonne
- Chile lets Codelco keep its profits for the first time since 1976, a fiscal decision that says more about the copper cycle than any forecast could
- Erbium’s price has climbed sharply since June as buyers accumulate ahead of a November 10 expiry of China’s suspended export controls, with holmium and ytterbium drawing the same precautionary buying
- De Beers is spending hundreds of millions arguing natural stones are worth 50 times a lab-grown twin, while Walmart sells diamond studs for $12 a pair
- Venezuela’s government and opposition file a joint request for the Bank of England to return 31 tonnes of gold worth around €4 billion
Why it matters: The buyers who ignore the price
Gold fell harder this spring than in any quarter of the past decade. Central banks responded by buying 289 tonnes, the most ever recorded in a second quarter and roughly five times the previous three months.
That is not a trade. Nobody managing a portfolio for return accumulates into a double-digit drawdown at that pace. It is a reserve allocation decision made by institutions that do not mark to market in any way that matters, and that are optimising for something other than price.
What they are optimising for is clarity about who can freeze their assets, which is why the buying accelerated after 2022 and has not stopped since.
This week supplied the illustration, with Venezuela’s government and opposition jointly asking the Bank of England to release 31 tonnes held in London, a reminder that custody and ownership are separate things. For private investors the read-through is narrower than the gold bugs would like.
A permanent, price-insensitive bid of roughly 850 tonnes a year is a genuine floor under the metal, and it explains why the majors trade at 12 to 14 times earnings with 5% yields while the commodity sits near records. It does not make gold a compounder.
It makes it an asset whose largest buyer has decided the price is not the point, which is a strange and rather comfortable thing to own alongside people who do care.
Farmland
- Lake Mead and Lake Powell hit record low levels together, squeezing water supplies for roughly 40 million people across seven states and edging closer to dead pool
- India’s monsoon is tracking around 90% of the long-period average, with the country’s own forecaster putting the probability of a below-normal season at 84%
- The monsoon is the first of El Niño’s three classic fingerprints to arrive, since the American signatures are winter phenomena whose seasonal windows have not opened yet
- Italy’s $4.7 billion cheese economy is straining as extreme heat drives up storage costs at the banks holding Parmigiano wheels as loan collateral
- Brazil’s October election will set policy for the top exporter of soybeans, coffee, beef and sugar, with both candidates promising more local processing
- Greenfield Robotics pitches autonomous weeding machines as the replacement for herbicides, betting the next agricultural transition is robots rather than bigger tractors
Why it matters: The Colorado River runs out of buffer
Lake Mead and Lake Powell have been declining for twenty-five years, and the story has been told so often that the numbers stopped registering. Both reservoirs hitting record lows in one month should register, because the system has no slack left in it.
Powell exists to protect Mead, Mead exists to deliver to the lower basin, and both are approaching the elevations where hydropower generation stops and then where water cannot pass through the dams at all.

Agriculture is where this lands first and hardest, since roughly 80% of Colorado River water goes to irrigation, and a large share of that grows alfalfa and other forage crops that are, in effect, a way of exporting western water as beef.
When allocations get cut, the cuts arrive by seniority of water right rather than by economic value, which is why the investable question here is never the crop and always the paper.
Farmland with senior, reliable, appurtenant water rights in a stressed basin does not trade like farmland. It trades like an option on everyone else’s shortage.
The same logic is running elsewhere in the same week, with India’s monsoon forecast at 90% of normal and Italy’s cheese banks paying up to keep their warehouses cool. Reliable water is becoming the scarcest input in agriculture. It is priced almost nowhere as if that were true.
Wine, Whiskey, and Spirits
- Burgundy begins its earliest harvest in nearly 500 years, pulling the region’s picking calendar forward by weeks against any historical baseline
- Diageo’s chief executive stands to earn as much as £20 million under a new package announced while the company cuts jobs and runs an £890 million restructuring
- Diageo reformulates its Indian whiskies and rum after India’s food regulator banned added flavourings, on the grounds that whisky flavour has no business being added to whisky
- Suntory targets £738 million of Indian sales by 2030, betting the demographic story outruns the global slowdown in spirits
- Court filings reveal distributor RNDC owes more than $400 million to roughly 100,000 creditors, after losing suppliers worth $3 billion in annual revenue within three years
- Rare whisky auction values have fallen about 40%, a correction that has now run long enough to look structural rather than cyclical
- French vineyard prices fall again with Bordeaux leading the decline, as regional sales drop below three million hectolitres for the first time in decades
Why it matters: Burgundy picks in August, again
A harvest date is the least glamorous number in wine and one of the most informative. Burgundy is bringing in its earliest crop in nearly five centuries, which is not a weather anecdote but a shift in where the region sits on the ripeness curve.
Grapes that once struggled to reach sugar levels now reach them weeks early, which raises alcohol, drops acidity and compresses the picking window into a narrow band where a few days of judgment decide the vintage.

Producers can adapt through canopy management, altitude and picking earlier still. What they cannot adapt to is the frost risk that comes with budding earlier every spring, and that is the mechanism that has repeatedly cut Burgundy volumes by a third or more in recent vintages.
For collectors the arithmetic is uncomfortable in a specific way. Scarcity supports price, and Burgundy has been the best-performing fine wine category of the past decade largely because there is so little of it.
But scarcity driven by climate volatility is not the same asset as scarcity driven by appellation rules, because it arrives with vintage variation that widens the gap between good years and bad.
That is happening while the rest of the category deflates, with Bordeaux vineyard values falling and rare whisky auction values down roughly 40%. Fine wine is barbelling exactly like art. The top gets scarcer and the middle gets cheaper.
Japan trip in 60 days
Three nights in Tokyo. One night in the Nagano highlands.
Our Japan trip is 60 days away, and we’re excited to share the trip is taking shape.
Updates:
- Hotels locked in: Cerulean Tower Tokyu Hotel (Shibuya) for 3 nights, Hotel Silk (Madarao) for our night in Iiyama
- Bonsai Day is fully confirmed: Shunkaen Bonsai Museum, a traditional tea ceremony, and a private live bonsai performance with renowned artist Mr. Saeki
- Sumo show is set. This is gonna be epic.
- Traditional tea ceremony in Shinjuku (matcha and sencha)
- Nagano day: Now includes the Jigokudani Snow Monkey Park before our distillery tour and tasting at Kiyokawa
- Vinyl hunting in Shimokitazawa added for those sticking around before departure


More details to come as we lock in the final pieces.
4 Spots Left
Tokyo, sumo, bonsai masters, snow monkeys, sake at a private distillery — this trip is going to be epic.
Early bird pricing is over, but you can still lock in before it’s fully booked.
- Price: $3,999
- Bring a guest: +$2,999
- Includes: All meals, drinks, activities, events, and transportation. Everything except flights.
Lock in your spot with a $1,000 deposit. Fully refundable up to 60 days before departure.
See you next time, Stefan
Disclosures
- This issue was sponsored by Rooftop Immersive
- has no sponsors and contains no affiliate links.